

Debt Payoff Planner & Tracker
by Easily get a plan and stick to it - OxbowSoft LLC
4.5
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.5
- Price
- Free
- Download
- 500.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
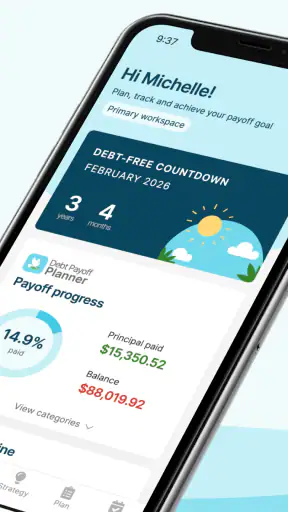
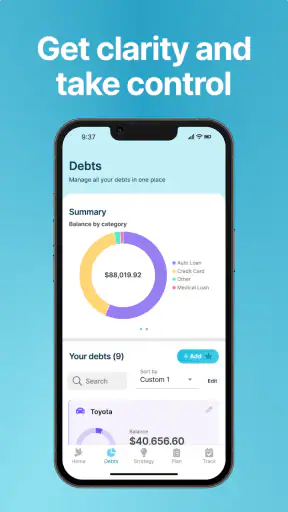
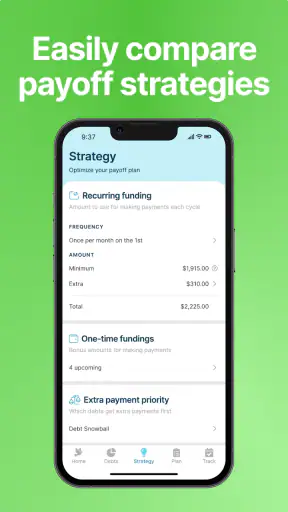
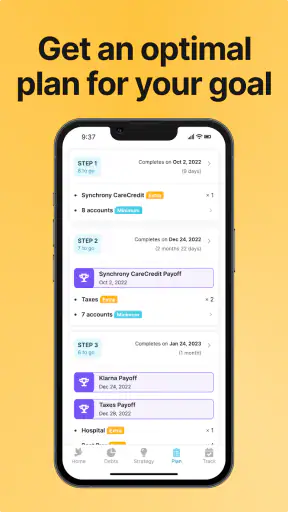
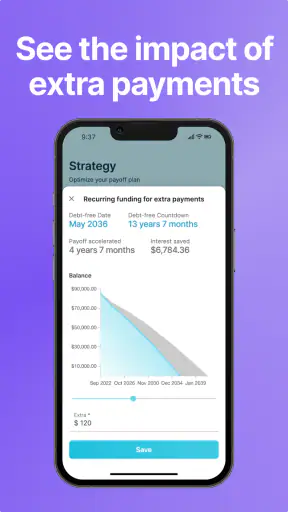
 Analysis by Getfullapps
Debt Payoff Planner & Tracker is the kind of finance app I would suggest to someone who has stopped avoiding their debt and wants one clear place to begin. Its purpose is not to replace a bank, negotiate with creditors, or magically reduce what you owe. Instead, it turns repayment into a visible plan: enter your debts, decide how you want to approach them, follow progress, and give yourself a reason to keep going.
I found the idea reassuring because debt often feels confusing when it is spread across cards, loans, and monthly bills. A written plan can make the situation feel less like a cloud hanging over you and more like a sequence of manageable decisions. The app is free to install, with optional in-app purchases priced from $6.99 to $41.99 per item, so a cautious first-time user can explore the basic experience before deciding whether extra paid functionality is worthwhile.
What to expect before you start
This is a debt payoff planner, not a full household budgeting suite. That distinction matters. If you are looking for detailed grocery tracking, investment analysis, bill negotiation, or bank-account automation, this is probably not the right tool. Its focus is narrower and, in my view, more useful for people whose immediate priority is reducing balances in a deliberate way.
The app comes from Easily get a plan and stick to it - OxbowSoft LLC. It has reached over 500 thousand installs and holds a 4.5 average from around 4.7 thousand ratings, which gives me some confidence that the concept works for a substantial group of users. It is rated for Everyone, and it runs on Android 6.0 or later. The current version is 2.54.
That broad compatibility is practical if you are using an older Android phone, although the experience may feel less polished than a newer, bank-connected finance service. I would approach it as a focused planning notebook with guidance rather than as an all-in-one financial dashboard. That expectation makes the app easier to appreciate.
The most important preparation is not technical. Before opening it, gather the current balance, interest rate, minimum payment, and payment date for each debt you want to include. You do not need to make the first session perfect, but entering vague guesses can produce a plan that feels precise while being unreliable. A few minutes spent checking statements will make the later progress view much more meaningful.
Why a focused planner can beat a general budget app
General budget apps are helpful when the main problem is overspending or a lack of awareness about monthly categories. Debt repayment has a different emotional rhythm. You need to know what to pay, why that order makes sense, and how each payment changes the remaining journey. A dedicated planner keeps that objective in front of you instead of burying it among restaurant purchases and subscription categories.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
I also like the separation between planning and banking. Automatic account connections can save time, but they can also make users feel that the app is doing the thinking for them. With a manual planner, you are forced to understand the numbers you enter. That adds effort, yet it can be valuable when you are trying to change habits rather than simply observe them.
The trade-off is that manual information needs maintenance. If an interest rate changes, a balance is transferred, or a payment is missed, the plan can become outdated unless you return and adjust it. Someone who wants every account synchronized automatically may be happier with a different finance product.
Setting up a useful first plan
My advice is to begin with only the debts you are actively managing. Add each account carefully instead of rushing through a long list. For a credit card, that usually means checking the statement for the balance, minimum due, interest rate, and next payment date. For a personal loan, use the figures from the lender’s current information rather than relying on memory.
Once the entries are in place, review the plan as a whole. The point is not to create an impressive-looking total; it is to see whether the proposed payments fit your real monthly life. If the plan requires money you regularly need for rent, food, transport, or essential bills, it is too aggressive. A smaller amount that you can repeat is more useful than an optimistic amount that collapses after one month.
This is one of the app’s less obvious strengths: it encourages you to treat repayment as a routine rather than a one-time burst of motivation. I would set the planned payment after looking at an ordinary month, not your best month. Occasional extra money can then be treated as a bonus instead of something the entire strategy depends on.
There is also a useful psychological advantage to entering debts separately. When everything is combined into one frightening number, progress can be hard to notice. Individual balances give you smaller milestones. Paying off one account may not change your overall finances dramatically, but it can remove one due date and simplify your monthly attention.
The first meaningful success
Your first success should not be installing the app or filling in every field. It should be completing a realistic plan and recording the first payment against it. That action turns the app from a calculator into a habit tool. I would choose a payment you can make without borrowing elsewhere, then update the relevant debt immediately afterward while the amount is still fresh.
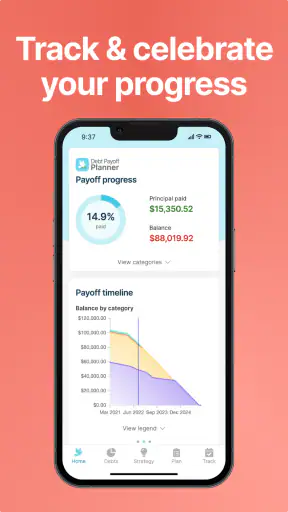
After recording that payment, pause and look at the progress rather than closing the app straight away. This is where the motivational side becomes useful. A visible reduction, even a modest one, gives you something concrete to return to. The app’s promise is built around planning, tracking, and celebrating, and that sequence makes sense: a plan tells you what to do, tracking proves that you did it, and recognition helps the routine continue.
A practical workflow is to update the planner on the same day as each payment. Do not wait until the end of the month and try to reconstruct everything from memory. If you make several payments, recording them separately can help you understand which actions are moving which balances. This also makes errors easier to spot.
For a realistic example, imagine that I have several debts and receive my monthly income near the start of the month. I would first check that the minimums and essential expenses are covered, then use the app to identify the planned target for the remaining repayment money. After making that payment, I would update the balance and leave a short note for myself about what changed. The next month begins with a current picture instead of another round of guessing.
That workflow is especially helpful for people who feel discouraged because their balance does not fall quickly. A repayment plan is not only about the final date. It can also reduce uncertainty, prevent forgotten payments, and show whether the amount you are contributing is consistent with your intention.
Confusion points worth understanding early
The first common confusion is assuming that a payoff plan automatically knows the exact future. It does not. The result depends on the accuracy of your balances, rates, minimums, dates, and planned payments. If a lender changes terms or adds a charge, the forecast should be treated as a guide until you update the entry.
A second confusion is mixing up a payment plan with a complete budget. The app can help you decide how to direct repayment money, but it cannot make an unaffordable monthly budget affordable. Before increasing a debt payment, check whether you have enough for essentials and whether an irregular expense is likely to arrive soon. A plan that ignores those realities can create a cycle of paying debt and then using credit again.
The third is expecting a single strategy to suit every situation. People often compare approaches that prioritize the highest interest rate with approaches that prioritize the smallest balance. The mathematically cheaper route is not always the one a particular person can maintain. If clearing a small account gives you the motivation to continue, that emotional benefit may matter. If interest costs are the central concern and you can stay disciplined, a rate-focused approach may be more attractive.
I would use the app to compare the practical consequences of your chosen order, then make the decision based on both money and behavior. The best plan is not necessarily the one that looks most impressive on paper. It is the one you will still follow when an unexpected expense, a stressful week, or a disappointing statement arrives.
Another point to watch is data entry. A wrong decimal, an old balance, or an omitted account can make the progress display misleading. I recommend checking the total against your latest statements before treating the plan as authoritative. This is a small habit, but it prevents false reassurance.
How to keep the planner useful after the first week
Once the first payment is recorded, use the app at a steady interval rather than repeatedly checking it throughout the day. A weekly glance can be useful for people who need encouragement, while a monthly update may be enough for someone whose payments are simple and predictable. Frequent checking is not automatically better; it can become another source of anxiety.
One advanced but simple tactic is to separate “planned” money from “extra” money in your own thinking. Build your normal plan around the amount you can reliably pay. When a bonus, refund, or unusually cheap month gives you more room, decide separately whether to apply it. This protects the core schedule from becoming dependent on occasional income and makes extra payments feel like progress rather than punishment.
I would also review the plan after any major change in your life: a new job, a move, a change in interest rate, or the payoff of one account. Removing a finished debt from your mental workload is important, but so is deciding where its former payment should go next. If you simply absorb that money into everyday spending, the plan may lose momentum without you noticing.
For couples or families, the app can be useful if one person takes responsibility for keeping the entries current and both people agree on the figures. It is not a substitute for a shared conversation. The strongest workflow is to review the plan together, agree on the monthly target, and avoid changing the numbers privately. That makes the tool a shared reference instead of a source of arguments.
On the other hand, I would skip it if you dislike manual updates, have a highly complicated financial situation, or need professional advice about insolvency, taxes, legal collection activity, or consolidation. A planner can organize information, but it cannot judge every financial risk. In those cases, a qualified adviser or a service with the relevant specialist support is a better next step.
Free access, paid options, and everyday practicality
Because the app is free, it is easy to try without committing money at the beginning. That matters for debt-focused software: I would not want to pay before discovering whether the planning style fits my habits. The optional purchases range from $6.99 to $41.99 per item, so anyone considering an upgrade should first identify the exact problem they are trying to solve.
My rule would be simple: do not buy extra functionality as a substitute for entering accurate numbers or making the first payment. If the basic workflow already helps you plan and track consistently, paid features may be worthwhile only when they remove a specific obstacle. If you are not returning to update the plan, spending more will not fix the underlying habit.
The app’s Everyone rating makes it approachable for a broad audience, but financial decisions still require adult judgment. Younger users may benefit from learning how balances and payments work, while anyone sharing a device or financial information should use ordinary phone security and avoid entering figures casually in front of others.
Compared with a spreadsheet, the app is more approachable and more motivating for someone who does not want to design formulas or formatting. A spreadsheet wins when you need custom projections, unusual debt structures, or complete control over every calculation. Compared with a notebook, this planner offers a clearer sense of changing balances, but a notebook may be better for someone who prefers writing and does not want another digital routine.
Compared with a bank’s own app, it is more focused on the overall payoff journey rather than one institution’s account. That makes it useful when debts are scattered across providers. The cost is that you must keep the information current yourself, whereas a bank app may show live account details for its own products.
Who will get the most from it
I think this app is best for a first-time planner who has several debts, wants a straightforward repayment direction, and benefits from seeing progress in one place. It is also a good fit for someone who has tried to “just pay extra when possible” and discovered that vague intentions are easy to postpone.
It can help users who are motivated by milestones, provided they understand that the milestones depend on accurate updates. It may also suit people who want to discuss repayment with a partner or family member because a visible plan gives the conversation something more concrete than worry.
I would be more cautious about recommending it to someone who needs automatic transaction imports, detailed spending categories, investment tools, or advanced household forecasting. Those needs point toward a broader financial management app. I would also avoid presenting it as a solution for debt that is already unmanageable. In that situation, organizing the numbers is useful preparation, but outside guidance may be more important than another tracking screen.
My recommendation after using the full workflow
What I like most about Debt Payoff Planner & Tracker is its narrow purpose. It does not ask you to become a finance expert before taking action. You collect the figures, create a repayment path, make a payment, and update the result. That sequence is simple enough to repeat, yet structured enough to replace vague promises with evidence.
Its main weakness is the same thing that gives it control: manual responsibility. If you want a hands-off experience, the need to maintain balances and terms may feel like work. The planner should also be treated as a practical guide rather than a guarantee, especially when rates or account conditions change.
My suggested first session is short and concrete: gather current statements, enter one accurate debt, add the others carefully, choose a payment that fits your real budget, and record the first completed payment. Then return on a predictable schedule instead of waiting for motivation. That first successful update is more valuable than spending an hour customizing a perfect plan.
Overall, I would recommend it to anyone who wants a dedicated, approachable way to turn debt repayment into a visible routine. It is free to begin, widely compatible, and supported by a 4.5 average from around 4.7 thousand ratings. Just remember what it is: a focused planner and tracker. Used honestly and updated regularly, it can make a difficult goal feel more organized. Used as a replacement for budgeting, professional advice, or accurate account information, it will disappoint.
Pros
- Clear payoff timelines make long-term debt goals easier to understand.
- Supports multiple debt accounts in one organized dashboard.
- Progress tracking can provide motivation as balances gradually decrease.
- Useful for comparing different repayment strategies before committing.
- Simple interface makes regular balance updates quick and manageable.
Cons
- Advanced planning features may require a paid subscription.
- Results depend on entering accurate balances, rates, and payment details.
- It does not make payments or negotiate directly with creditors.
- Users with irregular income may find fixed payoff projections less reliable.
- Some features may feel limited without connecting financial accounts.
FAQs for Debt Payoff Planner & Tracker
What is Debt Payoff Planner & Tracker used for?
Debt Payoff Planner & Tracker is designed to help you organize and manage personal debt in one place. You can enter balances, interest rates, minimum payments, and due dates, then review your repayment progress over time. The app can make it easier to compare payoff approaches, understand your overall debt load, and stay focused on reducing what you owe.
Can Debt Payoff Planner & Tracker calculate a repayment plan?
Yes, the app is intended to help you create a structured debt repayment plan based on the information you provide. It can show how different payment amounts or payoff strategies may affect your estimated completion date and interest costs. Results are only estimates, however, so they may change when rates, fees, balances, or payment schedules change.
What types of debt can I add to the app?
You can generally use Debt Payoff Planner & Tracker to track common debts such as credit cards, personal loans, student loans, medical bills, and other installment or revolving accounts. Each debt can be recorded with details such as the current balance, APR, minimum payment, and due date. The app is a tracking tool, so it does not automatically verify your lender information.
Does the app connect directly to my bank or creditors?
Debt Payoff Planner & Tracker is primarily intended for manually organizing debt information and monitoring progress. Depending on the version and available features, it may not connect directly to banks, credit-card providers, or loan accounts. Before relying on the figures shown, compare your entries with current statements and update balances, interest rates, and payments regularly.
Is Debt Payoff Planner & Tracker financial advice?
No. The app should be treated as a budgeting and debt-planning aid rather than a substitute for professional financial advice. Its projections depend entirely on the accuracy of your entries and may not include every fee, rate change, or creditor policy. If you are struggling with payments, consider speaking with a qualified financial counselor before making major repayment decisions.

Debt Payoff Planner & Tracker
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@debtpayoffplanner.com, visit https://www.debtpayoffplanner.com, or review their https://www.debtpayoffplanner.com/privacy-policy/.










